Toni Cowan-Brown asked what Wall Street needs to see to keep funding AI. Evans says AI-related debt this year runs somewhere between half a trillion and a trillion dollars, which changes who gets a say in how far the build-out goes.
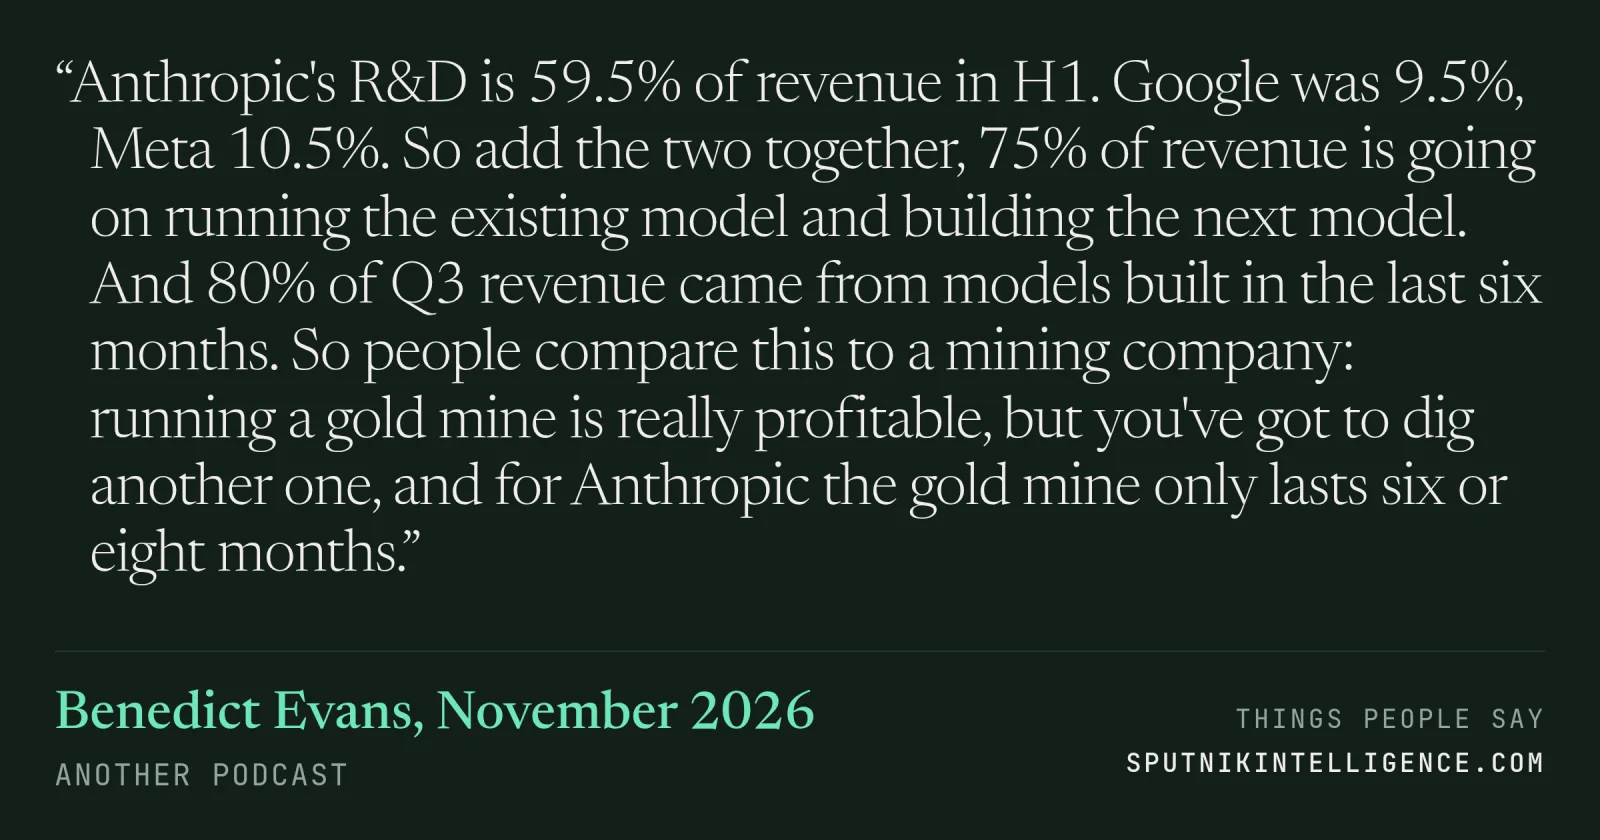
…this might be the thing. This might be a thing that people do. But how is it going to fit together? We don't know. Can you plot that back against Anthropic? No. Back to my point. This is a snapshot of the unit economics in the summer of 2026. That doesn't tell you how any of this is going to work.
It feels like one maybe last question that I know we touched upon a little bit, but what does Wall Street need to see to keep funding this? Where do you think their head is at? Like what, you know, what happens when we run out of capital? What's next here?
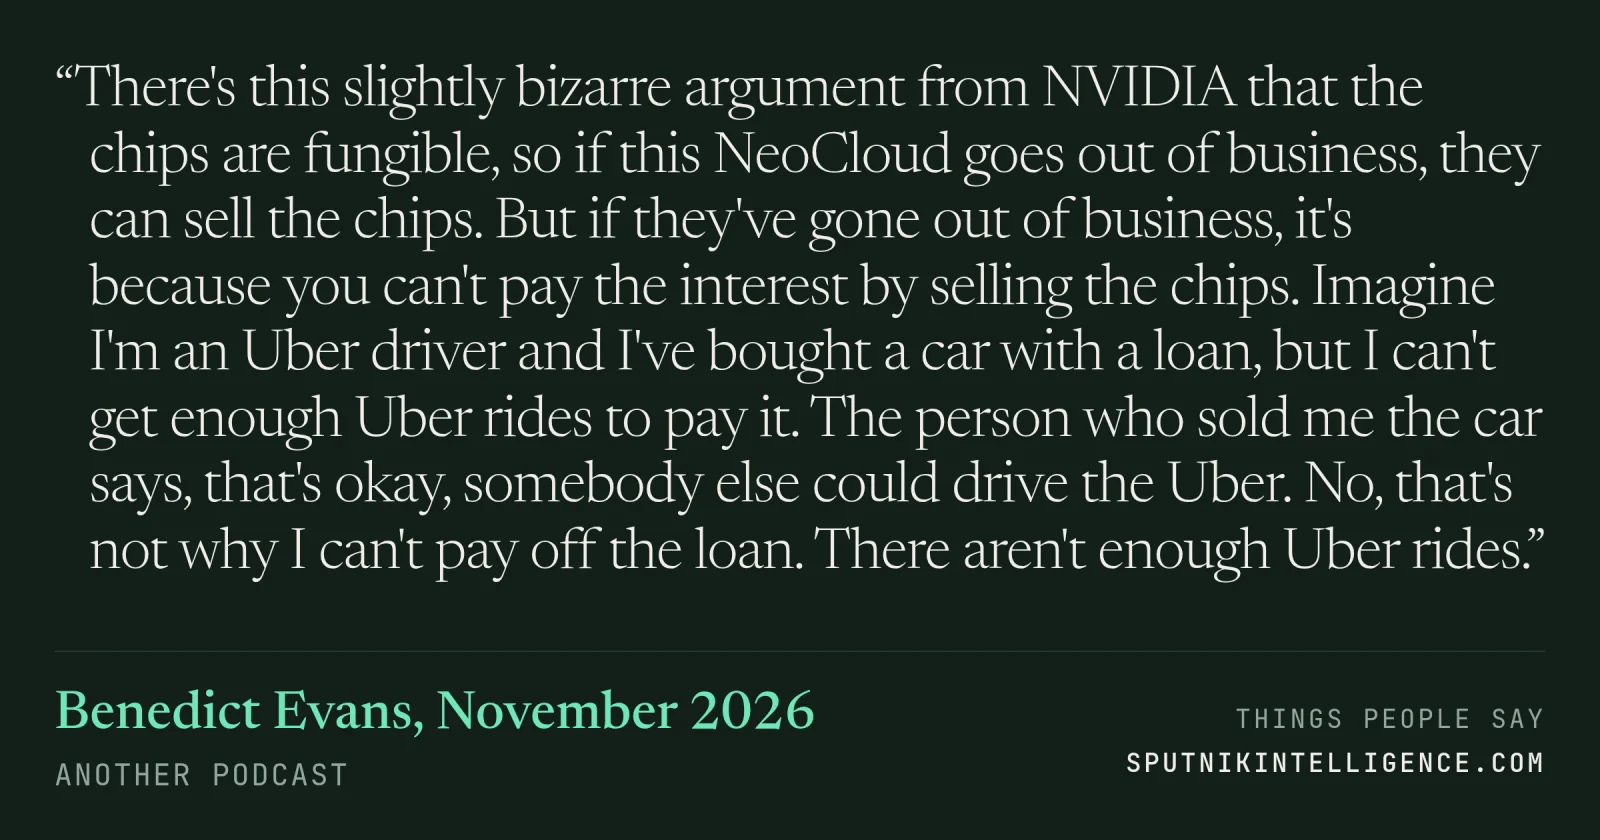
Well, so one of the things I think I've been saying, I can't remember we said it on the last podcast, is that there's sort of two fundamental changes in AI this year. One of them is the massive product market fit for software development, AI for software development. And the other is that the capex is outgrowing the free cash flows at the hyperscalers. So they can no longer fund this out of their existing businesses. And so depending on who you ask, you've had something. Like, where's my slide? Something between half a billion and a trillion, half a trillion and a trillion dollars of debt issued around AI this year. There's well over a trillion dollars of leases, well over a trillion dollars of future purchase commitments. The Google, the hyperscalers on one side, and then the NeoClouds and Oracle on the other side have had to go to the capital markets. And so that now means that it matters what the capital markets think, which it didn't in 2024. So that's just the primary observation. Secondly, it's funny. Like, I remember when I was an equity analyst, I would talk to the credit analysts and realize that I had no idea what…
looking at a population. And something from completely different angles.
Yeah, but look, look, it's a completely different question. Because as an equity analyst, as an equity investor, what you want to know is how much is the share price going to go up. Whereas as a credit investor, what you care about is do they have the cash flows to pay me? And you don't care how…
no pivoting from that. Yeah, I am.